When Prime Rises, the Biggest Smith Manoeuvre™ Risk Is Your Own Reaction
Prime moves up, and the next statement on your investment line of credit shows it. The interest charge that looked tidy on the planning spreadsheet is bigger now, and it competes with the groceries, the BC Hydro bill and everything else coming out of the same chequing account. Your mortgage might be fixed for three more years, yet this part of your debt changed with prime. A plan meant to slowly convert your mortgage into investment debt over decades suddenly feels like a problem you have to solve this month.
If you've opened that statement and wondered whether to scrap the whole strategy, you know how fast a planned debt can start to feel like a mistake. The common advice when rates rise is to cut your exposure: pay the line down, stop borrowing, sell some investments. Sometimes that is exactly right. The trouble is that the decision often gets made on the worst day to make it. What you need is a way to tell an interest increase you can carry from a real affordability problem. A higher rate is a reason to review your plan. It does not, by itself, tell you to quit, and it does not tell you to keep borrowing.
Why a higher interest bill doesn't mean the strategy has failed
A readvanceable mortgage pairs a regular mortgage with a secured line of credit. As you pay down principal, your borrowing room on the line can grow, subject to your lender's limits, with the combined total capped at 80% of your home's value. The line is usually priced at prime plus a spread, so when prime rises, your interest charge rises with it. That was always part of the deal.
Put a number on it. On an illustrative $100,000 investment line balance, a one-percentage-point rise adds about $1,000 a year, or roughly $83 a month, before any tax effect. That is a real cost, and on a tight budget it matters. Yet $83 a month is a figure you can plan around. A vague sense that "rates went up and everything is falling apart" isn't.
The risks here are genuine. Borrowing against your home to invest means your costs can climb while your investments fall. Panic adds its own damage on top of those risks. Selling after a market drop, just as borrowing costs peak, locks in the loss at the moment the strategy is most expensive.
How you pay the interest matters less than whether the plan still fits your budget
When the bill jumps, people fixate on how to pay it. Covering the interest from your own cash flow is a legitimate choice. Under CRA rules, deductibility depends mainly on what the borrowed money was used for, namely investing to earn income. Paying the interest from your paycheque does not erase that.
The other option is capitalizing the interest, meaning you borrow from the line to pay the line's own interest. That keeps your monthly budget steady, but the debt grows faster and uses up borrowing room, and that room has a ceiling. Interest on borrowed interest also comes with its own tax conditions, so confirm how your borrowing is traced and how any capitalization is set up with your mortgage professional and your tax adviser. A strategy's name and a tax deduction don't make every arrangement right for you.
Before the next rate move, set your review triggers. Pick a monthly interest figure your household budget can carry, and a minimum amount of borrowing room you want to keep. If either line gets crossed, you sit down and reassess. Because you set the limits ahead of time, you won't be reacting to a statement.
Staying calm doesn't oblige you to keep borrowing. It lets you look at the plan clearly and change it if it no longer fits. A sound plan should fit your household, and your household shouldn't have to strain to defend the plan. Start small: take your actual investment line balance, multiply it by 1%, divide by 12, and hold that monthly number up against your budget.

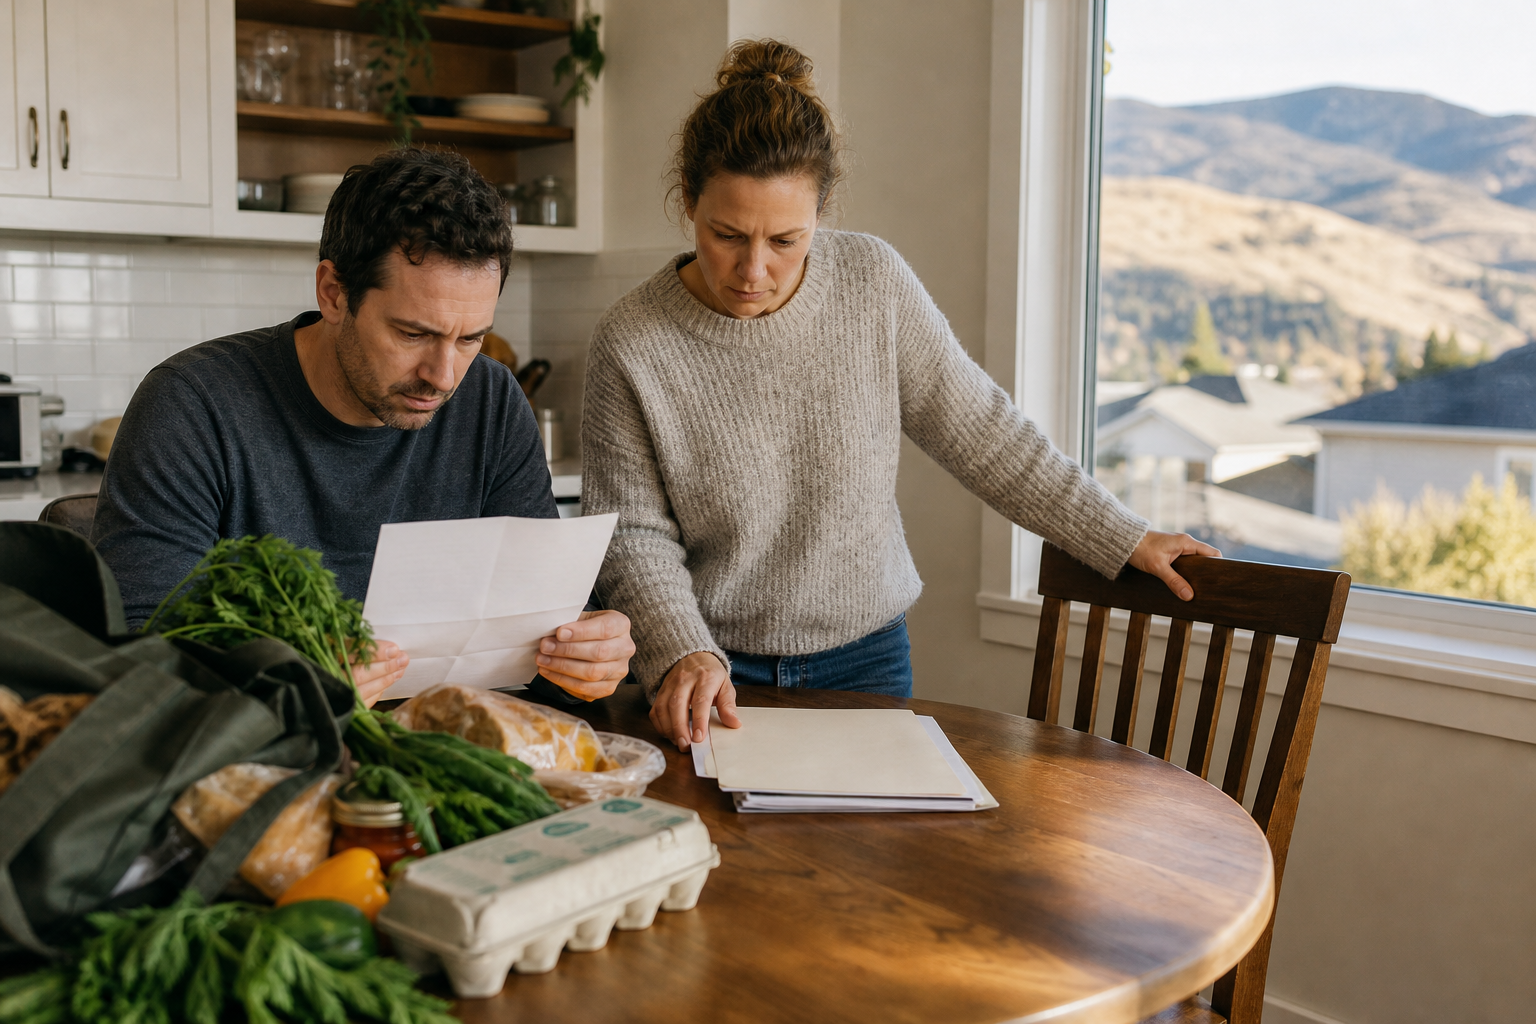
Prime moves up, and the next statement on your investment line of credit shows it. The interest charge that looked tidy on the planning spreadsheet is bigger now, and it competes with the groceries, the BC Hydro bill and everything else coming out of the same chequing account. Your mortgage might be fixed for three more years, yet this part of your debt changed with prime. A plan meant to slowly convert your mortgage into investment debt over decades suddenly feels like a problem you have to solve this month.
If you've opened that statement and wondered whether to scrap the whole strategy, you know how fast a planned debt can start to feel like a mistake. The common advice when rates rise is to cut your exposure: pay the line down, stop borrowing, sell some investments. Sometimes that is exactly right. The trouble is that the decision often gets made on the worst day to make it. What you need is a way to tell an interest increase you can carry from a real affordability problem. A higher rate is a reason to review your plan. It does not, by itself, tell you to quit, and it does not tell you to keep borrowing.
Why a higher interest bill doesn't mean the strategy has failed
A readvanceable mortgage pairs a regular mortgage with a secured line of credit. As you pay down principal, your borrowing room on the line can grow, subject to your lender's limits, with the combined total capped at 80% of your home's value. The line is usually priced at prime plus a spread, so when prime rises, your interest charge rises with it. That was always part of the deal.
Put a number on it. On an illustrative $100,000 investment line balance, a one-percentage-point rise adds about $1,000 a year, or roughly $83 a month, before any tax effect. That is a real cost, and on a tight budget it matters. Yet $83 a month is a figure you can plan around. A vague sense that "rates went up and everything is falling apart" isn't.
The risks here are genuine. Borrowing against your home to invest means your costs can climb while your investments fall. Panic adds its own damage on top of those risks. Selling after a market drop, just as borrowing costs peak, locks in the loss at the moment the strategy is most expensive.
How you pay the interest matters less than whether the plan still fits your budget
When the bill jumps, people fixate on how to pay it. Covering the interest from your own cash flow is a legitimate choice. Under CRA rules, deductibility depends mainly on what the borrowed money was used for, namely investing to earn income. Paying the interest from your paycheque does not erase that.
The other option is capitalizing the interest, meaning you borrow from the line to pay the line's own interest. That keeps your monthly budget steady, but the debt grows faster and uses up borrowing room, and that room has a ceiling. Interest on borrowed interest also comes with its own tax conditions, so confirm how your borrowing is traced and how any capitalization is set up with your mortgage professional and your tax adviser. A strategy's name and a tax deduction don't make every arrangement right for you.
Before the next rate move, set your review triggers. Pick a monthly interest figure your household budget can carry, and a minimum amount of borrowing room you want to keep. If either line gets crossed, you sit down and reassess. Because you set the limits ahead of time, you won't be reacting to a statement.
Staying calm doesn't oblige you to keep borrowing. It lets you look at the plan clearly and change it if it no longer fits. A sound plan should fit your household, and your household shouldn't have to strain to defend the plan. Start small: take your actual investment line balance, multiply it by 1%, divide by 12, and hold that monthly number up against your budget.
Read Next
Audit Your Own Rental Income Before the Lender Does: A Pre-Offer Checklist
The Bank of Canada Targets 2%, and Your Mortgage Plan Should Too
The CRA Ignores Your Collateral and Asks One Question: What Did You Buy?
5% Down or 20% Down: What the Smaller Deposit Costs Over 25 Years