The CRA Ignores Your Collateral and Asks One Question: What Did You Buy?
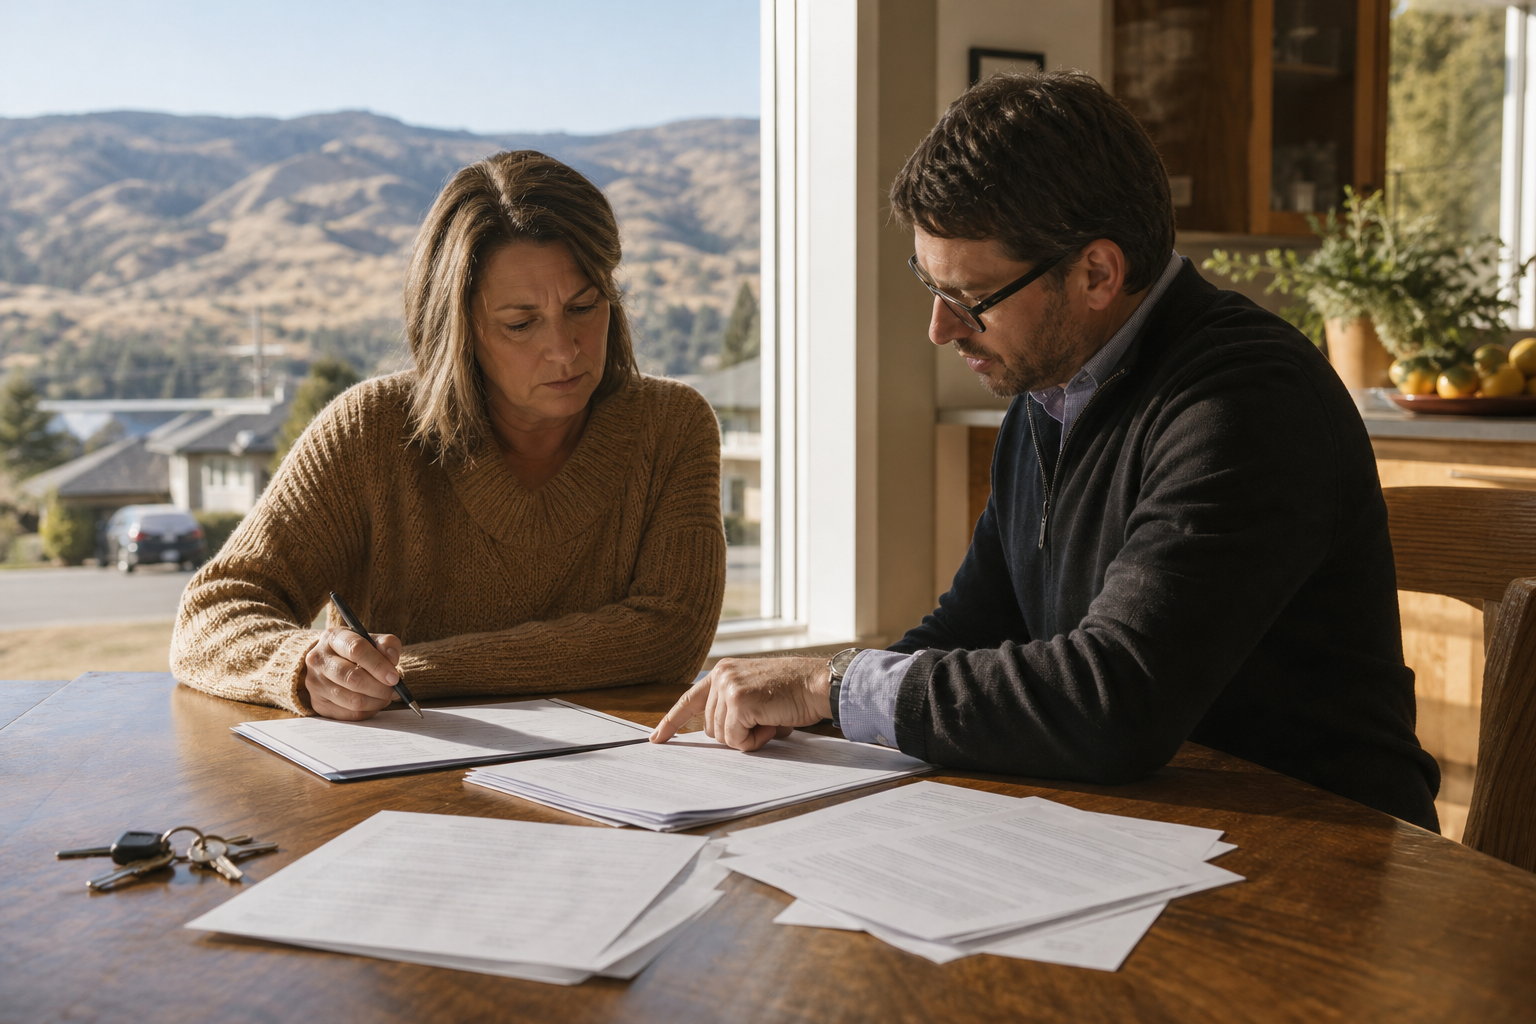
Picture a landlord in Vernon with a mostly paid-off rental and a large mortgage on the house she lives in. She refinances the rental, uses the cash to pay down her home mortgage, and expects the new interest to show up as a rental expense at tax time. The loan documents name the rental, so the interest feels like it belongs there. Under CRA rules it generally doesn't, because the money paid off a personal debt. Her after-tax borrowing cost ends up higher than the one she planned around.
If you've ever looked at a refinance secured by your rental and assumed the interest would be deductible, even though the money would pay down your own home, you know how easily a borrowing decision can rest on an untested tax assumption. Judging a loan by the property behind it works fine when you're comparing rates, lenders or how much you can qualify for. For tax, what counts is where the borrowed dollars go. Get that clear before you refinance, and you won't build a plan around savings you can't claim.
Why a loan against your home can qualify when a loan against your rental may not
Take two owners in BC. The first borrows against the equity in her own home and uses that money to buy a rental property that earns rent. The second takes extra cash out of his rental and uses it to pay down the mortgage on the house he lives in. The home-secured loan may qualify for an interest deduction. The rental-secured cash-out generally does not.
Paragraph 20(1)(c) of the Income Tax Act allows you to deduct interest on money borrowed to earn income from a business or property. In everyday terms, the borrowed money has to go toward something that can produce rent, dividends, interest or business income. Paying down your own home mortgage is personal, so interest on money used that way isn't deductible, whatever property sits behind the loan.
So follow what the borrowed money is used for, not the property securing the loan.
Use still isn't the only test. You must be legally obligated to pay the interest, the amount has to be reasonable, and you need a reasonable expectation of earning income. The second owner's original rental purchase loan doesn't lose its treatment either. Only the new personal portion is the problem.
How to show where your borrowed money went before anyone asks
Go back to those two owners. The first can point to a loan advance, a transfer and a property purchase. That chain of documents is what supports her claim. Only the interest can be deducted. Principal repayments never are.
Before borrowing, label each planned use as personal or income-earning. The property's name on the loan won't answer the tax question for you. Where it's practical, keep personal and income-earning borrowing in separate loan portions, such as separate sub-accounts or lines of credit. It makes splitting the interest and keeping records far simpler. Keep your loan statements, transfer records and purchase or expense documents together. Taken as a set, they show the link between the borrowing and what it paid for.
Mixing purposes in one account doesn't automatically wipe out a deduction. It does make tracing harder, and you'll have to show which dollars went where and split the interest accordingly. Some uses generally won't qualify at all. That includes personal spending, contributions to an RRSP or TFSA, and investments bought purely for capital gains with no potential to pay income.
Have a tax professional review the intended use, and any existing debt being replaced, before closing. A refinance doesn't automatically create a deduction or change how old debt is treated. A loan label and tidy records can't turn personal spending into income-earning use.
The one question to answer before you sign
Most borrowers ask which property should secure the loan. The better question is what this borrowed money will actually pay for. Before your next refinance, write the intended destination beside each proposed loan portion: rental purchase, renovation on the rental, paying down your home. Bring that outline to your tax professional before any funds are advanced.

Picture a landlord in Vernon with a mostly paid-off rental and a large mortgage on the house she lives in. She refinances the rental, uses the cash to pay down her home mortgage, and expects the new interest to show up as a rental expense at tax time. The loan documents name the rental, so the interest feels like it belongs there. Under CRA rules it generally doesn't, because the money paid off a personal debt. Her after-tax borrowing cost ends up higher than the one she planned around.
If you've ever looked at a refinance secured by your rental and assumed the interest would be deductible, even though the money would pay down your own home, you know how easily a borrowing decision can rest on an untested tax assumption. Judging a loan by the property behind it works fine when you're comparing rates, lenders or how much you can qualify for. For tax, what counts is where the borrowed dollars go. Get that clear before you refinance, and you won't build a plan around savings you can't claim.
Why a loan against your home can qualify when a loan against your rental may not
Take two owners in BC. The first borrows against the equity in her own home and uses that money to buy a rental property that earns rent. The second takes extra cash out of his rental and uses it to pay down the mortgage on the house he lives in. The home-secured loan may qualify for an interest deduction. The rental-secured cash-out generally does not.
Paragraph 20(1)(c) of the Income Tax Act allows you to deduct interest on money borrowed to earn income from a business or property. In everyday terms, the borrowed money has to go toward something that can produce rent, dividends, interest or business income. Paying down your own home mortgage is personal, so interest on money used that way isn't deductible, whatever property sits behind the loan.
So follow what the borrowed money is used for, not the property securing the loan.
Use still isn't the only test. You must be legally obligated to pay the interest, the amount has to be reasonable, and you need a reasonable expectation of earning income. The second owner's original rental purchase loan doesn't lose its treatment either. Only the new personal portion is the problem.
How to show where your borrowed money went before anyone asks
Go back to those two owners. The first can point to a loan advance, a transfer and a property purchase. That chain of documents is what supports her claim. Only the interest can be deducted. Principal repayments never are.
Before borrowing, label each planned use as personal or income-earning. The property's name on the loan won't answer the tax question for you. Where it's practical, keep personal and income-earning borrowing in separate loan portions, such as separate sub-accounts or lines of credit. It makes splitting the interest and keeping records far simpler. Keep your loan statements, transfer records and purchase or expense documents together. Taken as a set, they show the link between the borrowing and what it paid for.
Mixing purposes in one account doesn't automatically wipe out a deduction. It does make tracing harder, and you'll have to show which dollars went where and split the interest accordingly. Some uses generally won't qualify at all. That includes personal spending, contributions to an RRSP or TFSA, and investments bought purely for capital gains with no potential to pay income.
Have a tax professional review the intended use, and any existing debt being replaced, before closing. A refinance doesn't automatically create a deduction or change how old debt is treated. A loan label and tidy records can't turn personal spending into income-earning use.
The one question to answer before you sign
Most borrowers ask which property should secure the loan. The better question is what this borrowed money will actually pay for. Before your next refinance, write the intended destination beside each proposed loan portion: rental purchase, renovation on the rental, paying down your home. Bring that outline to your tax professional before any funds are advanced.
Read Next
Audit Your Own Rental Income Before the Lender Does: A Pre-Offer Checklist
When Prime Rises, the Biggest Smith Manoeuvre™ Risk Is Your Own Reaction
The Bank of Canada Targets 2%, and Your Mortgage Plan Should Too
5% Down or 20% Down: What the Smaller Deposit Costs Over 25 Years